8 interesting podcasts that are perfect if you want to learn something new

A man travelling on a bus with headphones on.

An Ofcom report found that just over 20% of UK adults now listen to at least one podcast a week. They can be a fantastic way to learn something new, whether you’re interested in trivia or want to delve into a specific topic.

So, if you’re looking for a new podcast, here are eight interesting ones that might capture your attention.

1. Ologies

Ologies with Alice Ward is a weekly science podcast that features an expert in a distinct scientific field each episode. So, there are plenty of opportunities to learn something new. Recent topics have included fireflies, sustainable ocean food, and maritime archaeology – you’re sure to find something that stands out to you.

2. Stuff You Should Know

This podcast has been around since 2008, and there are more than 1,500 episodes. The entertaining episodes are perfect if you have eclectic interests or want to be surprised every time you put your headphones on. Just a glance at the 2025 topics highlights the variety you can enjoy, with episodes looking at popcorn, MI6, editorial cartoons, and Richard III, to name a few.

3. 99% invisible

Roman Mars hosts this weekly podcast that takes a look at everyday objects you overlook to delve deeper into their design. Not only could you learn something new, but it might encourage you to start looking at the world closely.

With more than 600 episodes, there’s plenty to dig into, including a look at the Arsenal football stadium design, the history of public service announcements, and the story of a house that was sold as a kit and assembled by the owners.

4. Philosophize this!

If you haven’t studied philosophy, it can seem like a dense and complex topic, and you might not know where to start. These 20-minute episodes, put together by Stephen West, could help you see the world in a new light as you explore some of the ideas from the world’s greatest thinkers, from the wisdom of ancient Greek philosopher Aristotle to Nietzsche’s critiques of Western philosophy.

5. Carry the Two

Carry the Two is a podcast about maths and statistics, but don’t let that put you off if you’re not a numbers person. The hosts explain how mathematical research drives the world in simple language, so you won’t need to worry about calculating difficult equations.

Topics about how polls are conducted during elections or how science is portrayed in Hollywood could give you a new way to view maths.

6. Womanica

Women are often missing from history lessons taught in schools, and this podcast could help you fill in some of the gaps.

There’s a new episode every day that offers a quick way to learn about incredible women you might not know but should. Each month provides a theme, such as “rebels”, “mothers”, or “maritime”, so it’s a chance to learn about broader topics as well as individuals.

2. Grammar Girl

Grammar might not sound like the most exciting topic for a podcast, but don’t overlook this excellent chance to learn something new. Host Mignon Fogarty makes the topic engaging and interesting.

You don’t need to be a professional writer to benefit from the content. The tips could help improve your written communication, no matter your profession. The episodes are typically less than 30 minutes, and recent topics include how language evolves and how your brain processes metaphors.

8. No Such Thing As A Fish

If you’re a fan of the TV show QI, this is the perfect podcast for you – it’s created by the show’s researchers.

The weekly episodes began in 2014 and have been bringing listeners obscure facts ever since. Each episode, the presenters take it in turns to share their favourite fact they’ve come across this week. So, expect to hear about a variety of topics each time you tune in, from Egyptian irons to “Hammer of the Scots” Edward I.

Does your income make you a “Henry”? Here are some ways it could affect tax considerations

A group of friends dining outside.

High earners striving to build wealth, dubbed “Henrys” (high earner, not rich yet), may find their tax position changes drastically as their income grows. Being aware of your tax liability now and in the future could allow you to create a financial plan that helps you get more out of your money by potentially reducing your tax bill.

There isn’t a clear definition of how much you need to earn to be a Henry or what constitutes being “wealthy”. A huge range of factors could affect your financial position, from where you live in the UK to your long-term goals.

According to a February 2025 study from HSBC, people in the UK believe you need an average annual income of £213,000 to be wealthy. The figure is around six times the national average income and represents the top 4% of earners.

However, even people earning below this threshold could find they’re affected by high-earner tax rules. As a result, you may benefit from regular reviews.

If you’re a Henry, here are four tax rules that might affect your long-term finances.

1. The “60% tax trap” may affect you if your salary exceeds £100,000

A key tax implication of becoming a high earner is losing the Personal Allowance – the amount you can earn each tax year before Income Tax is due. This could mean you fall into the “60% tax trap”.

While there isn’t an official tax rate of 60% on earnings, tax rules may mean you end up paying more Income Tax than you expect. Indeed, a December 2024 report in the Financial Times suggests the number of people affected increased by 45% between 2021/22 and 2023/24.

For every £2 you earn above £100,000, you lose £1 of the Personal Allowance, which is £12,570 in 2025/26. So, once you’re earning £125,140 or more, you don’t have any Personal Allowance.

In real terms, this means for every £100 you earn between £100,000 and £125,140, you pay Income Tax of £40 and lose another £20 because of the tapering of the Personal Allowance. As a result, you’re effectively paying 60% tax on this portion of your income.

Depending on your circumstances, there are some steps you might take to beat the 60% tax trap, including:

  • Increasing your pension contributions
  • Making charitable donations from your salary
  • Using a salary sacrifice scheme, where you’d agree with your employer to give up a portion of your salary in return for other benefits, such as higher pension contributions or a company car.

It’s important to weigh up the pros and cons of these options, and there might be other ways to manage your Income Tax liability. Please get in touch if you have any questions.

2. Your pension Annual Allowance could fall to £10,000

The pension Annual Allowance is how much you can tax-efficiently contribute to your pension each tax year. For most people, the Annual Allowance is £60,000 in 2025/26.

However, the Annual Allowance is gradually reduced if you’re a high earner. If your threshold income is more than £200,000 or your adjusted income (your income plus the amount your employer pays into your pension) is above £260,000, you’ll normally be affected by the Tapered Annual Allowance. It reduces your Annual Allowance by £1 for every £2 your adjusted income exceeds the threshold.

The maximum reduction is £50,000. So, if your adjusted income is £360,000 or more, your Annual Allowance would be just £10,000.

As a result, it could significantly affect how you might effectively save for retirement.

3. Parents may pay the High Income Child Benefit Charge

Parents claiming Child Benefit may be subject to the High Income Child Benefit Tax Charge, if one of them earns more than £60,000 a year.

Importantly, the tax charge applies if one of the parent’s income exceeds the threshold, rather than the household income. So, if both parents worked and earned £55,000 each a year, the High Income Child Benefit Tax Charge would not be applied.

The Income Tax charge would be 1% of your Child Benefit for every £200 of income between £60,000 and £80,000. The charge will never exceed the amount of Child Benefit you receive and is usually paid through a self-assessment tax return.

While you wouldn’t receive any Child Benefit if you or your partner’s income exceeds £80,000, you may still claim it for National Insurance (NI) credit purposes. For example, if one partner is not employed because they’re caring for the child, claiming Child Benefit may mean they receive NI credits.

To receive the full State Pension, you usually need 35 years of NI credits on your record. As a result, claiming Child Benefit, even if you exceed the threshold, could be important for your or your partner’s future State Pension entitlement. While the State Pension often isn’t enough to retire on alone, it could still play a valuable role in your long-term financial security.

4. Inheritance Tax could reduce how much you leave behind for loved ones

If you’re still building wealth, it might feel too early to think about how you’d like to pass it on to loved ones in the future. Yet, establishing an estate plan now can be valuable and evolve as your wealth changes.

In 2025/26, the nil-rate band is £325,000. If the total value of your estate is below the threshold, no Inheritance Tax (IHT) would be due when you pass away.

In addition, some estates may be able to use the residence nil-rate band if the main home is left to direct descendants, such as your children or grandchildren. In 2025/26, this is £175,000. However, the residence nil-rate band is reduced by £1 for every £2 that the estate exceeds £2 million.

You can pass unused allowances to your spouse or civil partner, so an estate may be worth up to £1 million before IHT is due. Yet, the threshold for paying IHT could be significantly lower if you’re not estate planning with a partner or the estate isn’t eligible for the residence nil-rate band.

With a standard tax rate of 40% applied to the portion of the estate that exceeds the threshold, your loved ones could face a hefty bill.

The good news is that there are often steps you can take to reduce a potential IHT bill if you’re proactive. So, if you’re a Henry, making estate planning part of your tax considerations now could be useful in the long run and enable you to pass on more to your loved ones.

Contact us to talk about your tax liability

Reducing your tax liability now could mean you have more opportunities to invest or build long-term wealth, as well as potentially pass more on to your loved ones. If you’d like to create a tailored financial plan that considers your tax position, please get in touch.

Please note: This blog is for general information only and does not constitute financial advice, which should be based on your individual circumstances. The information is aimed at retail clients only.

Please do not act based on anything you might read in this article. All contents are based on our understanding of HMRC legislation, which is subject to change.

A pension is a long-term investment not normally accessible until 55 (57 from April 2028). The fund value may fluctuate and can go down, which would have an impact on the level of pension benefits available. Past performance is not a reliable indicator of future performance.

The tax implications of pension withdrawals will be based on your individual circumstances. Thresholds, percentage rates, and tax legislation may change in subsequent Finance Acts. 

The Financial Conduct Authority does not regulate estate planning or tax planning.

Unsure how to access your pension at retirement? Here’s what you need to know

A couple enjoying a bike ride.

It’s been a decade since Pension Freedoms legislation gave retirees more choice. Yet rather than relishing the freedom the changes have provided, research suggests workers are approaching retirement unsure about the decisions they need to make.

Data published by PensionsAge in June 2025 suggests that only 47% of UK savers are aware of their options in retirement. In addition, just 27% said they understood the reforms and the implications.

The decisions you make at the start of retirement could affect your financial security for the rest of your life. So, the research suggests a worrying number of retirees could pick an option that isn’t right for them because they don’t have all the information they need.

You can usually access defined contribution pensions from age 55. Read on to find out more about the three main options.

1. Purchase an annuity

If you’d prefer to receive a regular income that you know you can rely on, an annuity may be a valuable option.

You can purchase an annuity with the money held in your pension, and it would then provide an income for the rest of your life. You can choose if you want this income to remain the same or rise in line with inflation each year.

The annuity rate affects how much income you’d receive, and it’s influenced by a variety of factors, such as your age. Annuity rates can vary significantly between providers, so comparing options with your financial planner could help you achieve a higher income in retirement.

In addition, you can select a joint annuity, which would continue to pay your partner a portion of the regular income, such as 50%, if you pass away first. This could be a valuable option if you’re planning for retirement with a partner and they rely on your income.

2. Take a flexible income using flexi-access drawdown

You can also take a flexible income from your pension, so you might increase or decrease the amount you withdraw depending on your needs.

While this flexibility is attractive to many retirees, it’s important to consider how sustainable your pension withdrawals are. You’ll be responsible for ensuring you don’t run out of money in the future. According to PensionAge, 45% of survey participants said they worry that the ability to take a flexible income would leave them without enough.

The money that you don’t withdraw will remain in your pension and is usually invested. This means it has the opportunity to deliver long-term returns, but that your money is exposed to investment risk.

So, while flexi-access drawdown gives you more freedom to use your pension savings how you wish when compared to an annuity, it comes with potential drawbacks too. A retirement plan could help you balance your short- and long-term income needs when using flexi-access drawdown.

3. Withdraw lump sums

Finally, you can withdraw lump sums from your pension when you choose.

This could be a useful option when you want to boost your income for a one-off cost. In 2025/26, you can withdraw up to 25% of your pension tax-free, and you may choose to do that as a lump sum.

A June 2025 article in IFA Magazine found that more people are withdrawing lump sums from their pension as soon as they can. 120,000 people in the 12 months to the end of March 2024 did so, collectively accessing £2.2 billion.

While taking a lump sum can certainly be tempting, especially if it’s tax-free, you need to weigh up the pros and cons of doing so.

Taking a large amount out of your pension could mean you risk running out of money in your later years. Not only would the value of your pension be lower immediately, but it could also affect the long-term investment returns, which might mean you have less in your pension in the future than you anticipate.

You can mix and match the 3 ways of accessing your pension

You don’t have to choose just one of the above options when deciding how to create a pension income. You can mix and match – you might even decide to use all three.

For example, you might withdraw a lump sum at the start of retirement to kick off the next chapter of your life. You could use it to travel, renovate your home, or tick off some of the bucket list items you’ve been looking forward to.

Next, you might use a portion of your pension wealth to purchase an annuity that would create a reliable base income. Finally, you may access the money that remains in your pension flexibly and adjust the amount to suit your needs.

Your financial planner could help you assess which option is right for you

Even after understanding what your options are, it can be difficult to know which one is right for your retirement plans. However, according to the PensionAge report, just 29% of retirees said they would turn to a professional.

Working with your financial planner to create a bespoke retirement plan could mean you feel more confident accessing your pension and understand the effect your decisions might have. Please contact us if you have any questions about your retirement and accessing your pension.

Please note: This blog is for general information only and does not constitute financial advice, which should be based on your individual circumstances. The information is aimed at retail clients only.

Please do not act based on anything you might read in this article. All contents are based on our understanding of HMRC legislation, which is subject to change.

A pension is a long-term investment not normally accessible until 55 (57 from April 2028). The fund value may fluctuate and can go down, which would have an impact on the level of pension benefits available. Past performance is not a reliable indicator of future performance.

The tax implications of pension withdrawals will be based on your individual circumstances. Thresholds, percentage rates, and tax legislation may change in subsequent Finance Acts. 

Planning for care: Making later-life support part of your financial plan

A grandmother talking to her family.

While many people don’t rely on care later in life, planning for the potential cost of it could help you feel confident about the future and mean you have more options should you need support.

According to a December 2021 report from The Health Foundation, people are increasingly living healthier and more independent lives in their later years. Indeed, the proportion of older people who need social care has fallen.

However, as life expectancy has improved, the number of people who will need some form of care is likely to rise. The report suggests that between 2021 and 2046, the number of people aged over 85 in the UK will double to 2.6 million.

So, while needing care might not be certain, it’s important to plan for it. Last month, you read about some of the reasons why you might consider care now. Read on to discover how you may make it part of your wider financial plan.

Calculating a potential care bill

It can be difficult to calculate how much care services could cost. After all, it’s impossible to know what’s around the corner. Setting out your preferences and doing some research could be valuable.

To start, you might consider different scenarios to understand how you’d feel about the options. For example, you may answer questions like:

  • If you’d benefit from nursing care, would you prefer to receive this in your own home or a care home?
  • If you moved to a retirement village or care home, are there facilities you’d like to be near or have on-site?
  • Could your family or other loved ones provide support if you lived independently, or would you be able to move in with them?

With your preferences set out, you can start to calculate how much the different options may cost. The cost of care varies significantly across the UK, so doing some research in your local area alongside reviewing average figures could be beneficial.

Don’t forget you’ll need to consider how the cost of care is likely to change over the long term due to the effects of inflation.

When planning for care, it’s also important to consider a range of scenarios. If you only expect to get by with minimal support that your family could provide, you could find yourself in a difficult situation if your needs are more complex.

Being thorough when creating a care plan may mean you have more options should you need care and, hopefully, reduce financial worries at a time that might already be difficult.

4 ways you could cover care costs

There are many ways you might cover the cost of care. Here are four of the main options you could incorporate into your long-term financial plan.

1. Ringfence a portion of your wealth

Perhaps the simplest option is to ringfence a portion of your wealth for care costs. For example, you might earmark a portion of your savings or investments for care should it be needed.

2. Create a regular income

Another option is to create a regular income that would be enough to cover care costs.

You might do this by purchasing an annuity with your pension, which would then pay an income for the rest of your life. Alternatively, you might adjust your investment portfolio to create an income stream.

Your financial planner could help you assess how to create an income that offers reassurance about the future if you need care.

3. Take out long-term care insurance

It’s also possible to take out insurance that will pay a regular income if you need long-term care. The income may be paid directly to your care provider.

If you’re considering this option, it’s important that you understand the terms and conditions before taking out insurance. For instance:

  • What is the maximum monthly income it would pay out?
  • Are there any restrictions on which care providers you can use?
  • Under what circumstances would you be eligible to make a claim?

You may need to pay regular premiums to maintain the cover, which will vary depending on a range of factors, including your health and lifestyle. In some cases, you might make a one-off payment instead.

4. Use your property

Your home might be one of the largest assets you own. According to the Halifax House Price Index in June 2025, the average home in the UK was worth almost £300,000. So, if you’re thinking about how to fund a potentially large care bill, don’t overlook property.

There are several ways you might use property wealth to fund care.

If you’re moving into a care home, you might choose to sell your property to cover the cost.

Alternatively, you may use equity release to access some of the money tied up in your property without selling it. This could be a useful option if you want to remain living in your home.

However, there are drawbacks to consider before choosing equity release. The most common type of equity release is known as a “lifetime mortgage” and involves taking out a loan against your home.

With a lifetime mortgage, you don’t have to make any repayments, and the interest is rolled up. Instead, the loan is repaid when you pass away or move into long-term care. As a result, the amount owed could be significantly higher than the amount you initially borrowed and could affect the inheritance you leave for loved ones.

Seeking tailored advice could help you understand whether equity release is right for you.

Contact us to discuss your care plan

If you’d like to review your existing care plan or would like our support creating one, please get in touch.

Next month, read our blog to discover some of the steps you might take to ensure your wishes around care are followed.

Please note: This blog is for general information only and does not constitute financial advice, which should be based on your individual circumstances. The information is aimed at retail clients only.

The value of your investments (and any income from them) can go down as well as up, and you may not get back the full amount you invested. Past performance is not a reliable indicator of future performance.

Investments should be considered over the longer term and should fit in with your overall attitude to risk and financial circumstances.

Equity release will reduce the value of your estate and can affect your eligibility for means-tested benefits.

A lifetime mortgage is a loan secured against your home. To understand the features and risks, ask for a personalised illustration.

10 adrenaline-fueled adventures you can have in the UK

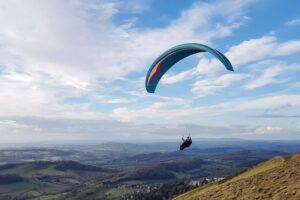
A person hang gliding.

Your favourite summer activity might be relaxing in the gorgeous sunshine, but it is also the perfect time of year to embark on an adventure.

From zip lines to abseiling into caves, the UK boasts an endless number of extreme sports and thrilling activities.

If you’re looking for a fun way to spend a day with your loved ones this summer, read on to discover 10 adrenaline-fueled adventures that will get your heart pumping.

1. Zip World, Bangor

Ride the 3 km Velocity zipline above Penrhyn Quarry to experience the longest zipline in Europe and the fastest in the world, reaching speeds of over 100 miles an hour.

Take in the fantastic views of Eryri before flying down one of the four parallel lines, which allow you to ride alongside your loved ones.

If Velocity might be too daunting for you, Zip World also offer gentler zip lines as well as a quarry tour if you prefer to keep both your feet on the ground.

2. Thruxton Circuit, Andover

Many places in the UK offer supercar driving experiences, but Thruxton Circuit is one of the best.

Once you’ve been trained in how to drive racing cars, you can drive and ride in six vehicles worth more than £800,000 in total, including the Ferrari 458 Spider and McLaren 5705.

To finish a day of white knuckle racing, you also get to ride in a high-speed two-seat racing car, driven by the iconic British racing driver and Top Gear presenter Tiff Needell.

3. Bridge bungee jump, Whitby

You might know Whitby for its world-famous fish and chips, stunning beach, or historical significance thanks to the iconic Whitby Abbey. But did you know it is also home to the only bridge bungee jump in England?

Experience the incredible thrill of leaping off the Larpool Viaduct and falling 42 meters over the gorgeous water.

4. Hang gliding, Bannau Brycheiniog

The grassy field and hills of this Welsh national park are ideal for gliders, paragliders, and hang gliders to soar over.

If you have a license, this is the perfect destination to spread your wings. But if you’re new to hang gliding, you can also visit the local Crickhowell Paragliding school, where you can embark on unforgettable tandem flights or learn how to become a pilot.

5. Virtual reality experiences, across the UK

If you’d rather keep yourself out of danger while still getting an adrenaline rush, you might enjoy a free-roam virtual reality experience.

These games are carefully designed so you can walk around a room unobstructed, interacting with the virtual world in completely immersive environments.

Meetspace VR have locations all over the country, including:

  • Nottingham
  • London
  • Birmingham
  • Reading
  • Manchester
  • Guildford
  • Bristol

Choose from a wide range of games, from fighting zombies, travelling through space, or walking through a topsy-turvy world where gravity doesn’t apply.

6. Skydive Northwest, Cumbria

Although many places offer skydiving experiences in the UK, Skydive Northwest’s excellent safety record and its incredible views of the Lake District make it a great option.

Freefall at speeds of 120 miles an hour from up to 15,000 feet and enjoy the stunning views of Lake Windermere and Morecambe Bay from the sky.

7. Dancing Ledge coasteering, Dorset

Dancing Ledge is one of the most popular coasteering venues in the UK and for good reason.

The company can tailor the experience to the group attending as their route along the Jurassic Coast boasts jumps of all heights, as well as caves to explore and swim through, making it perfect for families and thrill-seekers alike.

8. White water rafting, Aberfeldy

Splash Rafting offers a range of water activities in Perthshire, including the opportunity to white water raft down the River Tay.

The rafting trip is about six miles in distance and allows you to practise your new rafting skills with some fun challenges before the river drops away and you have to navigate a series of challenging rapids.

If you prefer a gentler water activity, they also offer paddleboarding, kayaking, and river duckies, which are a cross between a white water raft, a kayak, and a Canadian canoe.

9. Cornwall Underground Adventures, Cornwall

Combine a history lesson about Cornwall’s mining heritage with an exciting underground adventure by going below the surface and discovering the subterranean world carved out by centuries of Cornish miners.

Their easiest trip is perfect for families with children over the age of 10 and ventures into an ancient mine, with the opportunity to abseil down a few levels if you’re brave enough.

Or, if you want to push yourself, you can embark on their vertical caving trip where you use ropes to traverse across shafts and climb along the walls of gaping chasms of a 16th-century mine.

10. Ultimate Indoor Paintballing, Liverpool

If you have ever fancied shooting your loved ones, this might be the activity for you.

The firm offers a range of paintballing games, including capture the flag and free-for-alls. Every activity can be tailored for different age groups, making it perfect for a children’s party or a team bonding day for your colleagues.

For smaller children aged four and up, they also run Nerf Liverpool with fully padded crash mat walls, flooring, and obstacles to ensure everyone’s safety.

5 powerful Warren Buffett lessons that could benefit ordinary investors

A man looking at a graph showing stock market performance on his phone.

After more than five decades at the helm of Berkshire Hathaway, legendary investor Warren Buffett has announced he’s retiring at the age of 94. He’s credited with turning the failing textile maker into a successful holding company. In May 2025, the BBC estimated Berkshire Hathaway was worth $1.16 trillion (£870 billion).

Considered by many to be the most successful investor of the 20th century, Buffett has regularly featured on lists of the world’s wealthiest people, despite giving away vast sums.

While Buffett has a huge number of resources at his disposal, many of his idioms may be useful for ordinary investors, including these five.

1. Invest with a long-term view

Throughout his career, Buffett has focused on the potential long-term value of stocks and shares.

Indeed, he said: “If you aren’t willing to own a stock for 10 years, don’t even think about owning it for 10 minutes.”

It’s a useful reminder that trying to generate quick returns could lead to investors missing out on long-term gains. With so many different factors influencing the value of investments, it’s impossible to consistently time the market.

While investment markets often experience short-term movements, historically, they have delivered returns over longer time frames. Investors who plan to hold investments over the long term could benefit as a result.

2. Avoid investing FOMO

Buffett earned the moniker “oracle of Omaha” for his ability to make long-term investment decisions, and he did it without following the crowd.

Investing FOMO (fear of missing out) leads some people to invest in a way that doesn’t align with their strategy because they believe investments are “good” or “safer” if others are choosing them. However, making investment decisions based solely on what others are doing may be harmful.

Buffett once said: “When everyone wants in on it, that’s probably not the right time to jump in.”

When everyone is talking about the latest stock that’s sure to deliver big returns, the buzz has often already led to prices rising. As a result, following the latest trends could lead to disappointment.

It’s also important to note that what is a “good” investment for one person may not be right for another. As your circumstances and goals will play a role in your investment strategy, acting based on FOMO might mean you make investment decisions that don’t align with your financial plan.

3. Invest in what you know

Buffett once advised budding investors that they didn’t have to be experts in every company, but only had to evaluate companies within their “circle of competence”. In other words, stick to what you know, even if an opportunity outside of your knowledge sounds enticing.

Recognising when you could benefit from expert advice or support is beneficial too.

Buffett considered this when thinking about his estate plan. He’s instructed the trustee of his estate to invest 90% of his money into a passive fund, so his wife doesn’t need to make investment decisions day-to-day.

As a financial planning firm, we could help you create a balanced investment portfolio that you can have confidence in, including if you want to take a hands-off approach.

4. Don’t be seduced by a “bargain”

Finding a bargain, whether you’re out shopping or assessing investments, can be thrilling – everyone wants to get something for less if they can. However, looking only at the price when you’re weighing up an investment opportunity might mean you make a decision that isn’t right for you.

Instead, look at the bigger picture. How would the investment fit into your wider portfolio, and does it align with your investment goals?

As Buffett said: “It’s far better to buy a wonderful company at a fair price than a fair company at a wonderful price.”

5. Make investing part of your wider financial plan

When you’re setting out or reviewing an investment strategy, it can be easy to look at it in isolation. Yet, by making it part of your wider financial plan, you could improve the decisions you make.

For example, your financial circumstances and goals will play a role in your investment risk profile. Incorporating these areas when weighing up investments could help you strike a balance that suits your needs. Without this approach, you could find yourself taking more risk than is appropriate.

Buffett once noted: “It is insane to risk what you have and need to obtain what you don’t need.”

Contact us to talk about your investment strategy

An investment strategy that’s been tailored to your needs could lead to returns that help you reach your long-term goals. Please get in touch to talk to us about your investments.

Please note: This blog is for general information only and does not constitute financial advice, which should be based on your individual circumstances. The information is aimed at retail clients only.

The value of your investments (and any income from them) can go down as well as up and you may not get back the full amount you invested. Past performance is not a reliable indicator of future performance.

Investments should be considered over the longer term and should fit in with your overall attitude to risk and financial circumstances.